Zerodha CEO Supports New MDR for UPI Payments Amid Concerns
Zerodha's Perspective on Merchant Discount Rate
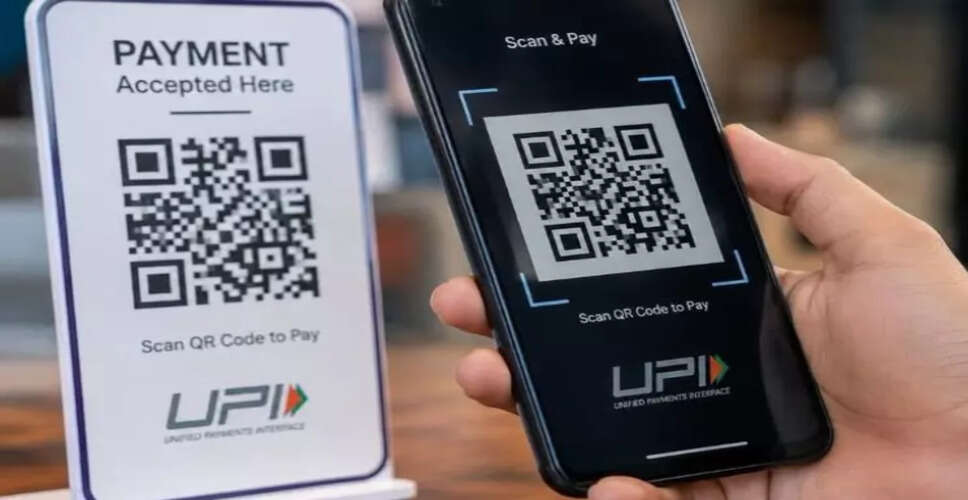
Representational Image of UPI(Photo: @Dreams_realites/X)
New Delhi, Sep 16: Nithin Kamath, the CEO of Zerodha, expressed his support for the newly implemented Merchant Discount Rate (MDR) on UPI payments from individuals to merchants, suggesting that it may be necessary due to the growing popularity of digital payments.
In a recent post on the social media platform X, Kamath noted that the introduction of MDR could help mitigate the current dominance in the UPI market, where a mere three applications control over 95% of transactions.
He stated, "The implementation of MDR on UPI was likely unavoidable, especially considering the extensive adoption of UPI. This could foster increased competition in the sector," in his post on X.
Nonetheless, he cautioned that the proposed MDR framework might not be appropriate for all scenarios, particularly in the realms of investing and brokerage.
Kamath highlighted that brokers cannot ensure that funds transferred to their accounts via UPI will lead to actual transactions. As brokers cannot compel clients to trade after funds are deposited, they risk incurring costs without any corresponding revenue if they cannot transfer the UPI fees to their clients.
For example, he illustrated that if 10,000 clients made 50 UPI transfers of Rs 2 lakh each in a month without executing any trades, it could potentially cost a broker around Rs 2 crore under the new MDR.
He also pointed out the implications of quarterly settlement requirements, which mandate that brokers return any unused client funds.
“The challenge is compounded by quarterly settlement (QS) regulations from SEBI, which require brokers to return unutilized funds to clients every month or quarter,” he explained.
Kamath noted that clients frequently transfer these funds back to their brokerage accounts, with over half of these transactions occurring through UPI.
He concluded that this situation could lead to brokers incurring UPI fees on multiple fund transfers without generating additional revenue.